Compute NEER and REER Using Free CPI and Exchange Rate CSVs
2026-09-07
NEER (nominal effective exchange rate) measures a currency’s value against a basket of trading partners without adjusting for inflation, while REER (real effective exchange rate) takes that same nominal index and deflates it by relative price levels. REER is the number economists actually trust for judging competitiveness, because a currency can look stable in nominal terms while quietly losing ground once you account for prices at home versus abroad.
TL;DR:
- REER provides a more accurate measure of currency competitiveness by adjusting NEER for domestic inflation differences.
- Divergences between NEER and REER reveal whether inflation or nominal exchange rates are driving competitiveness trends.
- Methodological choices, such as base year selection and trade weights, significantly influence the calculation and interpretation of both indices.
- Revisions to CPI or exchange rate data can cause retroactive shifts in REER, affecting its reliability as a long-term indicator.
- Building a custom REER requires careful selection of inflation and exchange rate data, which platforms like Fiatmap facilitate with accessible datasets.
Table of Contents
- Neer vs Reer: Starting With What NEER Actually Measures
- Neer vs Reer: Why REER Adds the Inflation Layer
- Neer vs Reer: The Formulas and Methodology Choices That Shape Both
- How to Read a Divergence Between the Two Indices
- How Central Banks and Analysts Put NEER and REER to Work
- Where NEER and REER Fall Short
- Building Your Own NEER and REER With Fiatmap Data
- A Practitioner’s Take on Reading These Indices
- Where to Pull Real CPI and Exchange Rate Data for Your Own REER Model
- Sources
Neer vs Reer: Starting With What NEER Actually Measures
NEER is a weighted geometric average of a currency’s exchange rate against every major trading partner, rolled into a single reserve currency argument index. Rather than tracking one bilateral pair, like the dollar against the euro, NEER blends dozens of pairs at once, weighted by how much each partner matters to trade flows.
The weights come from trade volume, export share, or some combination of both. A country doing 20% of its trade with a neighbor will assign that neighbor roughly 20% of the index’s influence, while a marginal trading partner barely moves the needle.
Reading NEER is straightforward once you know the baseline: a rising index means nominal appreciation against the basket, and a falling index means nominal depreciation.
- NEER rises when a currency strengthens on average against its weighted partners.
- NEER falls when it weakens on average, even if it gains against one or two individual currencies.
- The index is set to 100 (or another base value) in a chosen base year, so all later readings are relative, not absolute.
Picture a country trading equally with two partners. If its currency gains 10% against one partner’s currency and loses 4% against the other, NEER moves somewhere in between, weighted by trade share, not by a simple average of the two.
Neer vs Reer: Why REER Adds the Inflation Layer
REER takes the NEER calculation and adjusts it for the price gap between the home country and its trading partners, usually using CPI or the Harmonized Index of Consumer Prices (HICP) as the deflator. The logic is simple: if your currency holds steady in nominal terms but your domestic inflation runs hotter than everyone else’s, your exports quietly get more expensive anyway.
That inflation adjustment is what makes REER a purchasing-power measure rather than a pure currency-value measure. Two countries can show identical NEER trends and completely different REER trends, purely because one has faster consumer price index growth.
- REER rises (real appreciation) when domestic prices rise faster than trading-partner prices, even without any nominal currency movement.
- REER falls (real depreciation) when domestic inflation runs cooler than partners’, making goods relatively cheaper abroad.
- Divergence between NEER and REER often shows up during high-inflation periods, when the nominal rate looks calm but the real rate is sliding.
An increase in REER generally signals a loss of price competitiveness for domestic goods, according to Investopedia’s breakdown of the real effective exchange rate, because foreign buyers now pay more in real terms even if the exchange rate itself barely budged.
Neer vs Reer: The Formulas and Methodology Choices That Shape Both
The NEER formula is a weighted geometric average: NEER = Π(eᵢ)^wᵢ, where eᵢ is the bilateral nominal exchange rate against partner i, and wᵢ is that partner’s trade weight, with all weights summing to 1. REER extends this by multiplying NEER by the ratio of domestic to foreign price levels: REER = NEER × (P_domestic ÷ P_foreign), typically calculated using CPI or HICP indices for both sides.
Three methodological choices shape how any given series behaves:
- Base year selection. Every index needs a reference point set to 100; comparing two REER series with different base years without rebasing them is a common analytical mistake.
- Trade weights versus export weights. Some central banks weight by total trade, others by exports only, or by “double export weights” that account for third-market competition, and Eurostat’s methodology notes on effective exchange rates walk through exactly how that choice changes the result.
- Update frequency. NEER can be published daily or monthly since it only needs spot exchange rates, while REER typically lags to monthly or quarterly because CPI data arrives slower and gets revised.
Statistic callout: The Reserve Bank of India expanded its NEER/REER currency basket from 36 to 40 currencies and updated its base year, a rebasing exercise documented in the RBI Bulletin on NEER and REER methodology, illustrating how even a well-established index gets periodically reworked as trade patterns shift.
How to Read a Divergence Between the Two Indices
When NEER and REER move together, the story is simple: the currency is genuinely strengthening or weakening, in both nominal and real terms. The interesting cases are when they split apart.
- NEER flat, REER rising: domestic inflation is outpacing trading partners, eroding competitiveness even though the currency itself hasn’t moved.
- NEER falling, REER flat or rising: the currency is nominally depreciating, but inflation is offsetting the competitive benefit that depreciation would normally deliver.
- NEER rising, REER rising faster: both nominal strength and inflation are compounding, a combination that tends to draw central bank attention because it signals a double hit to export pricing.
For exporters, a rising REER means goods cost more for foreign buyers even without a change in quoted price, which usually compresses margins or market share over time. For policymakers, REER trends factor into decisions on interest rates, since IMF analysis of real exchange rates treats REER as a trade-weighted, price-adjusted signal of overall alignment, even though it can mask problems with individual trading partners.
Pro Tip: When REER shifts sharply in a short window, check the underlying bilateral rates and inflation data before assuming the whole currency is misaligned. A single trading partner’s price shock can swing the aggregate index more than the headline number suggests.
How Central Banks and Analysts Put NEER and REER to Work
Central banks treat REER as a diagnostic tool for external balance, not a trading signal. It answers a slower question: is this currency broadly overvalued or undervalued relative to the basket of countries it trades with, and does that call for policy attention?
- Institutions rebase their indices periodically, updating both the base year and the currency weights as trade patterns shift, the same kind of update the RBI made when it expanded its basket.
- Trade-weighted and export-weighted variants get published side by side, since exporters and import-competing sectors respond to slightly different exposure.
- Neither index is built for short-term timing. A REER reading tells you about medium-term competitiveness trends, not next week’s currency direction, which is why analysts treat sudden index moves as a prompt to investigate, not a trading trigger.
Real policy rate comparisons across countries, tracked here by country, often move alongside REER shifts, since interest rate decisions and currency competitiveness are tightly linked in most policy frameworks.
Where NEER and REER Fall Short
REER is an average, and averages hide detail. A country can show a REER sitting comfortably near equilibrium while running a significant bilateral overvaluation against one major partner and an equally significant undervaluation against another, a blind spot noted directly in the IMF’s own explainer on real exchange rates.
- Nontradable sectors (housing, local services) can distort the price indices feeding REER without reflecting anything about traded-goods competitiveness.
- Productivity gaps between countries, sometimes called the Balassa-Samuelson effect, can push REER higher for reasons that have nothing to do with currency misalignment.
- Because REER depends on CPI or HICP inputs, revisions to those price series can retroactively shift REER readings, a documented sensitivity in Eurostat’s own methodology.
- Absolute index levels aren’t comparable across providers using different base years or basket compositions, per the BIS effective exchange rate database.
Building Your Own NEER and REER With Fiatmap Data
Fiatmap’s country pages carry the raw ingredients for a hands-on NEER or REER exercise: inflation rankings by country, CPI definitions, and real policy rate comparisons across 128 countries.
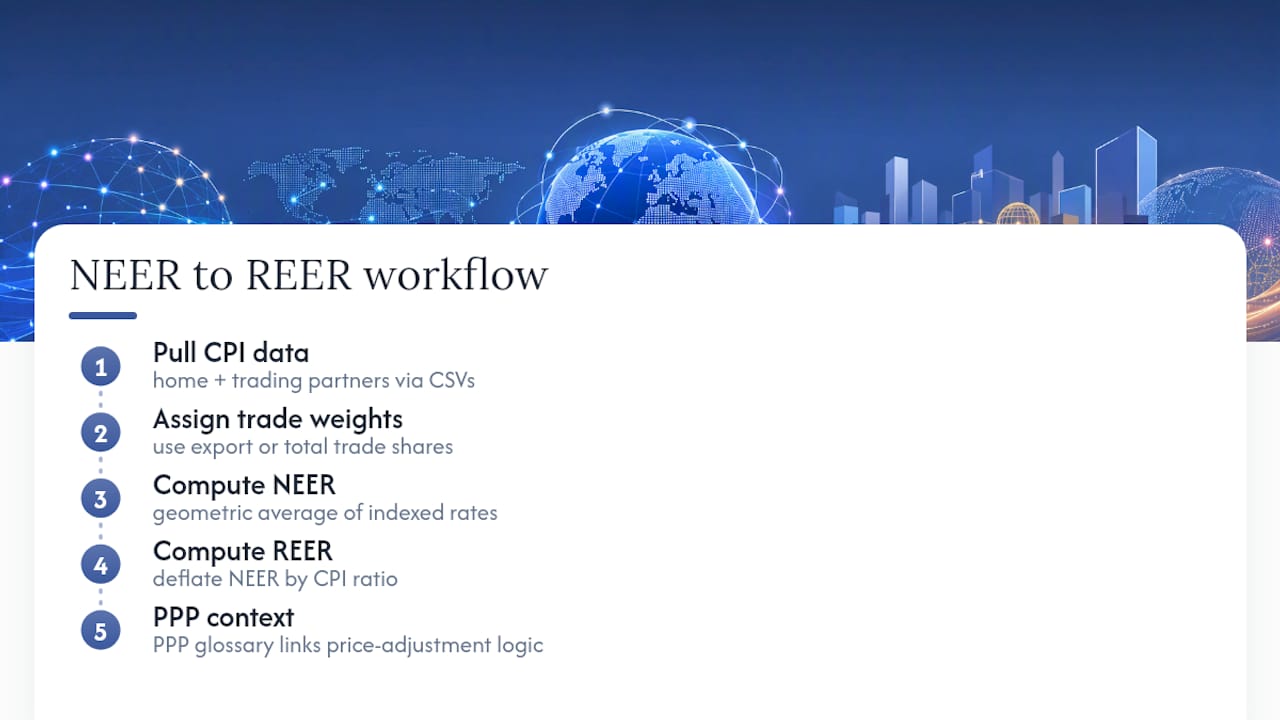
A basic workflow looks like this: pull CPI data for the home country and its main trading partners, assign trade weights based on export or total trade share, compute the geometric average to get NEER, then deflate that figure by the CPI ratio to arrive at REER. Fiatmap’s downloadable CSV files make the first step painless, and the platform’s purchasing power parity glossary entry helps connect the price-adjustment logic back to familiar PPP concepts for anyone building the calculation from scratch.
A Practitioner’s Take on Reading These Indices
Students lean on NEER because it’s simpler to compute, but REER is the number that actually answers the competitiveness question, and treating them as interchangeable is the most common mistake I see in early analysis. My advice: never let a smooth REER chart lull you into skipping the bilateral check. Average measures forgive a lot of hidden imbalance. Pull a country’s individual trading-partner rates before drawing conclusions from the aggregate, and use a hands-on dataset to build the index yourself at least once. Computing REER by hand, even crudely, teaches you more about weighting choices than reading ten explainer articles.
— Torstein
Where to Pull Real CPI and Exchange Rate Data for Your Own REER Model
Building an accurate REER series takes clean inputs, and that’s where a lot of student and analyst projects stall out searching for consistent CPI and exchange rate figures across countries. This problem can be solved by getting inflation, CPI, and real rate data for many countries pulled from official sources in one place.

The FiatMap Global Money Dataset is free to download in CSV or JSON, licensed under CC BY 4.0, so you can run the actual NEER and REER calculations described above without hitting a paywall. If you’re teaching or presenting this material, Fiatmap’s embeddable widgets let you drop a live inflation or exchange-rate map straight into a classroom slide or a research note. Start by pulling the CPI series for your base country and two or three trading partners, then build the weighted index from there.
Sources
- Real Effective Exchange Rate (REER): Definition, Formula, and Importance
- Real exchange rates: what money can buy — IMF
- Eurostat — Metadata on NEER/REER methodology
- RBI Bulletin — NEER and REER methodology and usage
Recommended
The figures on this site are collected from official statistics and each carries its own source and date — see /sources and the dataset. Where this article states a number, the country and ranking pages are what it should agree with.