When 6% Nominal Still Loses: Real Interest Rates With Fiatmap Data
2026-09-10
The real interest rate is the nominal interest rate minus inflation, and it measures whether your money actually grows or quietly shrinks. When inflation runs hotter than the rate a bank or bond pays, the real return turns negative and savers lose purchasing power even as their account balance climbs. That single number, more than the advertised rate, determines whether borrowing is cheap and whether saving pays off.
TL;DR:
- Real interest rates are most accurate when inflation remains below 5%, as higher inflation causes the approximation to overstate actual returns.
- To calculate the real rate precisely, use the exact Fisher formula, especially during periods of high inflation, instead of relying on the simple subtraction.
- Negative real rates are common when inflation surpasses nominal interest rates, benefiting borrowers and governments but eroding savers’ purchasing power.
- Federal Reserve, Treasury, IMF, and World Bank data sources provide accessible real interest rate figures across different maturities and countries.
- Monitoring current real rates is more vital than headline nominal rates, as inflation fluctuations can mask the true cost of borrowing or the value of savings.
Table of Contents
- What Is the Real Interest Rate? The Fisher Equation Explained
- How to Calculate Real Interest Rate: A Step-by-Step Walkthrough
- Where to Find Current Real Interest Rate Data
- Who Wins and Who Loses When Real Rates Turn Negative
- Comparing Real Interest Rates Across Countries With Fiatmap
- Why Real Rates Deserve More Attention Than Headlines Give Them
- Explore Real Rates and Mortgage Data on Fiatmap
- Sources
- FAQ
What Is the Real Interest Rate? The Fisher Equation Explained
Economists define it through the Fisher equation: (1 + i) = (1 + r)(1 + π), where i is the nominal rate, r is the real rate, and π is inflation. Rearranged, the exact real rate is r = [(1 + i) / (1 + π)] − 1.
Most people skip that division and use the shortcut r ≈ i − π. It works fine at low inflation, but it breaks down as prices rise faster.
- Below roughly 5% inflation, the approximation stays close enough to the exact figure for everyday use.
- At higher inflation levels, the gap widens, and relying on subtraction alone can overstate your real return by a meaningful margin.
- Taxes complicate things further: a saver taxed on nominal interest income pays tax on a return that inflation has already eaten into, which pushes the after-tax real interest rate lower still.
That gap between the clean formula and what actually lands in a saver’s pocket is why the distinction between nominal interest rates and real ones matters far beyond a textbook definition.
How to Calculate Real Interest Rate: A Step-by-Step Walkthrough
Calculating a real rate takes three decisions before you touch a formula.
- Pick your nominal rate: a savings account APY, a bond yield, or a policy rate from a central bank.
- Pick an inflation measure: the Consumer Price Index for consumer purchasing power, or the GDP deflator for a broader economy-wide gauge.
- Apply either the exact Fisher formula or the subtraction shortcut, depending on how high inflation is running.
Example A, low inflation: a savings account pays 3% nominal interest while inflation sits at 2%. The approximation gives 3% − 2% = 1%. The exact formula gives (1.03 / 1.02) − 1 = 0.98%. Nearly identical, so the shortcut works.
Example B, high inflation: a bond pays 6% nominal while inflation runs at 9%. The approximation gives negative 3%. Both signal the same story, that the saver is losing ground, but the gap between the two methods widens noticeably at this level.
That negative outcome is not rare. Real rates go negative whenever inflation outpaces the nominal rate, and several major economies spent extended stretches there through the early 2020s.
One more distinction matters: ex-ante real rates use expected inflation, calculated before the fact, while ex-post rates use actual realized inflation after the period ends. For ex-ante estimates, analysts often use the TIPS breakeven method, comparing a nominal Treasury yield against its inflation-protected counterpart of the same maturity.
Where to Find Current Real Interest Rate Data
You don’t need a Bloomberg terminal to track real rates. A handful of public sources cover almost everything.
- FRED, the Federal Reserve Bank of St. Louis database, hosts real interest rate series across multiple maturities that update automatically as new data arrives.
- The U.S. Department of the Treasury publishes par real yield curve rates derived directly from TIPS market prices, giving you a market-implied real yield without doing any math yourself.
- The Federal Reserve’s H.15 release lists selected nominal interest rates daily, which you can pair with a current inflation reading to build your own real-rate estimate.
- The World Bank DataBank defines the real interest rate using the lending rate adjusted by the GDP deflator, useful when comparing countries that don’t report CPI-based figures consistently.
- The IMF and ECB both publish plain-language explainers on how policy rates translate into real borrowing and savings conditions.
One caution: match your nominal maturity to the right inflation window, and watch for indexation lag. TIPS adjust their principal for inflation with roughly a three-month delay, so a TIPS yield is a close proxy for the real rate, not a perfect one.
Who Wins and Who Loses When Real Rates Turn Negative
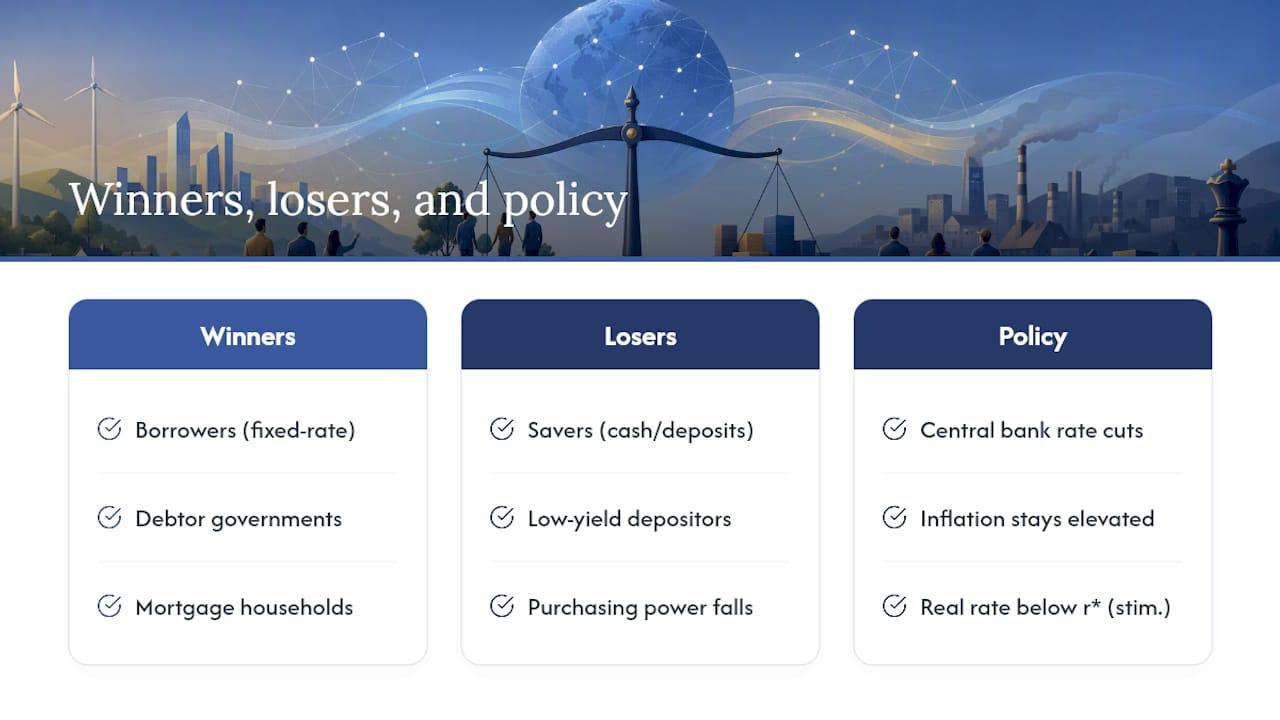
Negative real interest rates redraw the map of winners and losers overnight. Savers holding cash or low-yield deposits watch their purchasing power erode even while their account statement shows a gain. Borrowers come out ahead, because they repay their loans in money that’s worth less than what they originally borrowed.
Governments carrying large debt loads benefit the same way households with mortgages do: a negative real rate effectively shrinks the real burden of that debt over time, which is one reason some policymakers tolerate mild inflation rather than fight it aggressively.
Central banks pull the lever that starts this whole chain. When a central bank cuts its nominal policy rate and inflation stays elevated, the real policy rate falls, sometimes below zero, which is designed to encourage borrowing and spending rather than saving.
Economists also track something called r-star (r)*, the neutral or equilibrium real interest rate at which an economy grows at full capacity without triggering excess inflation or a slowdown. When actual real rates sit below r*, policy is stimulative. When they sit above it, policy is restrictive. Central banks debate r* constantly because nobody can observe it directly. It has to be inferred from growth, employment, and inflation data.
Pro Tip: If you’re deciding between a fixed-rate savings product and a variable one, check the current real deposit rate first. A high nominal rate during a high-inflation period can still leave you worse off in real terms than a lower rate during calm inflation.
Comparing Real Interest Rates Across Countries With Fiatmap
Real rates don’t move in lockstep across borders. A saver in one country can earn a healthy real return while a saver in another loses ground on an account paying a higher nominal rate. Fiatmap’s real policy rate map lays out country-level comparisons pulled from official statistics, so you can see at a glance where nominal rates outpace local inflation and where they don’t.
The platform’s tools go further than a single map:
- The real deposit rate comparison shows where savers are actually gaining ground versus losing it to inflation.
- Every dataset is downloadable in CSV or JSON, so you can build your own models instead of trusting a static chart.
- Embeddable widgets let you drop a live macro map directly into a report or analysis without manually updating figures each month.
For a plain-language starting point before diving into the maps, the real interest rate glossary entry walks through the definition with country examples attached.
Why Real Rates Deserve More Attention Than Headlines Give Them
Most financial coverage fixates on the nominal number because it’s simpler to report. That’s backwards. Heading into 2026, with inflation paths still uneven across major economies, the gap between nominal headlines and real outcomes is exactly where savers and borrowers get caught off guard. Check the real rate, not just the advertised one, and update that check monthly rather than assuming last quarter’s numbers still hold.
— Torstein
Explore Real Rates and Mortgage Data on Fiatmap
Once you understand how real interest rates work, the next useful step is seeing how they actually play out across countries rather than in a textbook example. Some platforms pull mortgage rates, inflation figures, and dozens of other macroeconomic metrics from official statistics across many countries, enabling comparisons based on verified numbers instead of guesswork.

If you’re weighing whether a mortgage rate in one country actually beats another after adjusting for local inflation, the global mortgage rate rankings let you sort by country instead of relying on a single lender’s marketing page. Pair that with the full Fiatmap dataset download, free and sourced entirely from official statistics, and you can build your own real-rate comparisons instead of waiting for someone else to publish them. Start by pulling the data for the countries you care about and running the Fisher equation yourself.
Sources
For readers who want to dig into primary data rather than secondhand summaries, a few sources cover almost everything discussed here.
- What are negative interest rates (IMF F&D)
- Real interest rate — Wikipedia
- Interest Rate Statistics | U.S. Department of the Treasury
FAQ
What’s the Difference Between Nominal and Real Interest Rates?
The nominal rate is the stated interest rate before any adjustment, while the real rate subtracts (or divides out) inflation to show the actual change in purchasing power.
How Do I Find the Real Interest Rate?
Subtract an inflation measure like CPI from the nominal rate for a quick estimate, or use the exact Fisher equation, (1 + i) / (1 + π) − 1, for precision. FRED and the U.S. Treasury’s par real yield curve rates both publish ready-made series if you’d rather skip the math.
Will We Ever See a 3% Mortgage Rate Again?
Rather than guessing, track mortgage rate trends by country alongside inflation data to see how real borrowing costs are actually shifting.
Which Country Currently Has the Highest Real Interest Rate?
This changes regularly as central banks adjust policy and inflation readings shift, so there’s no fixed answer worth stating here. Fiatmap’s real policy rate map tracks current country-by-country figures pulled from official statistics, updated as new data arrives.
Can Real Interest Rates Be Negative?
Yes. Whenever inflation exceeds the nominal rate, the real rate turns negative, which erodes savers’ purchasing power while effectively reducing what borrowers repay in real terms.
Recommended
The figures on this site are collected from official statistics and each carries its own source and date — see /sources and the dataset. Where this article states a number, the country and ranking pages are what it should agree with.